 Reading Time: 9 minutes
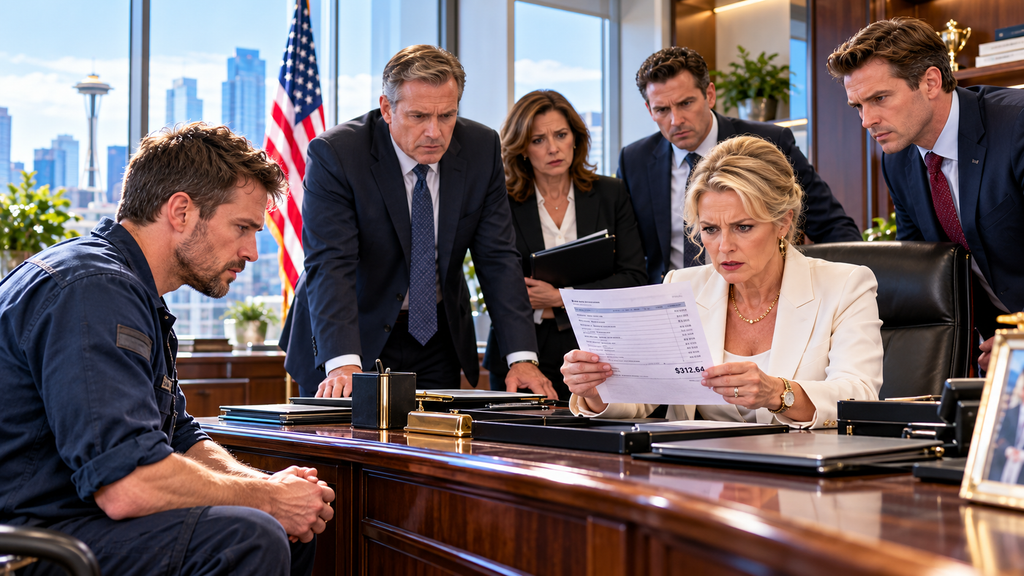
When the CEO asked why I was leaving, I quietly placed my latest pay stub on her desk. Claire Sterling glanced at the number at the bottom. Then she looked again. $312.64. For several seconds, she said nothing. Then she picked up her desk phone. “Get Finance and HR up here. I also want Derek Vance and Blake.” She paused. “No. I mean right now.” That was the moment my resignation turned into something much bigger than I ever imagined.
Blake read it. “Employee accountability adjustments.”
“Explain it without the corporate slogan.”
Blake sat down.
“Project overruns were increasing. Managers needed a way to discourage preventable losses. The accountability program was designed to make employees more careful about decisions that affect costs.”
Claire looked at him.
“Did Evan cause the problem at Apex?”
Blake hesitated.
“Not directly.”
“Did he choose the sensors?”
“No.”
“Approve installation?”
“No.”
“Then why did he lose thousands of dollars?”
“Because field service owns the customer outcome.”
Martin interrupted.
“What written authorization supports these deductions?”
Brenda opened her folder.
“Employees acknowledged the accountability policy.”
“Did Evan authorize these specific amounts?”
“No separate authorization.”
“Who independently verified that he caused the loss?”
Brenda hesitated.
“Operations reviewed the responsibility classification.”
Martin stared at her.
“So Operations assigned the responsibility, initiated the deduction, and confirmed its own decision?”
Nobody answered.
Claire rubbed her forehead.
“Why hasn’t any of this appeared in our employee-relations reports?”
Brenda shifted in her chair.
“Most complaints were categorized as routine payroll inquiries.”
Claire looked up sharply.
“Routine payroll inquiries?”
“Yes.”
“So employees could dispute being charged for something they didn’t cause, and the reports I received would show ordinary payroll questions?”
Brenda said nothing.
Claire turned toward me.
“Why didn’t anyone tell me?”
For the first time, I felt angry.
“People did complain.”
“Not to me.”
“You’re the CEO.”
“That shouldn’t matter.”
“But it does.”
I took a breath.
“I disputed charges twice. HR sent both complaints back to Derek. He confirmed his own decisions, and HR closed the cases.”
Claire looked at Brenda.
“Is that true?”
Brenda searched her laptop.
A minute later, she found the emails.
“Yes.”
Claire stared at the screen.
For a moment, she looked genuinely ashamed.
“I kept asking whether employee complaints were being resolved,” she said quietly. “I never asked who was deciding they were resolved.”
Then she turned to Martin.
“How much money has been deducted under this program?”
Martin began typing.
“I can pull a preliminary total from the payroll codes, but it won’t tell us which deductions were justified.”
“Do it.”
Brenda supplied the relevant codes.
Project accountability.
Customer responsibility.
Tool assessment.
Documentation penalty.
Attendance adjustment.
Martin ran the query.
His expression changed.
“That’s higher than I expected.”
“How much?” Claire asked.
“Over $1 million in the last 3 years.”
The room went silent.
Blake immediately leaned forward.
“That doesn’t mean $1 million was improperly deducted.”
Martin nodded.
“Correct. This is only a preliminary figure.”
Claire looked at the screen.
“How many employees?”
Martin typed again.
“214.”
I felt sick.
I knew other technicians had been affected.
I hadn’t imagined the scale.
Claire turned toward Derek.
“Walk me through Apex.”
Derek shrugged.
“The customer had downtime. Evan serviced the equipment. Operations allocated a portion of the costs to field service.”
“Was there a software defect?”
“Not exactly.”
“What does that mean?”
Derek hesitated.
“The internal classification was broader than the technical diagnosis.”
I opened my folder.
Sarah’s words came back to me.
Take pictures of everything.
I handed Claire the customer-signed service report.
She read it carefully.
Then she compared it with the internal allocation form.
“Why does one say there was no software defect while the other assigns Evan responsibility for a configuration problem?”
Derek looked toward Blake.
Blake answered.
“The internal form wasn’t intended to replace the technical report. It was a cost-accountability classification.”
Claire looked at Derek.
“Did Evan agree with it?”
“No.”
“Did anyone outside Operations review the technical evidence?”
Derek didn’t answer.
“Were the sensor and wiring issues later confirmed?”
Blake finally spoke.
“Yes. Production changed some specification controls afterward.”
“So there was a confirmed upstream problem.”
“Yes.”
“Did Evan’s deductions get reversed when you discovered that?”
Silence.
Claire looked at Martin.
“Freeze new deductions under these codes immediately.”
Blake sat forward.
“You cannot shut down an entire program over one disputed case.”
Claire turned toward him.
“I’m not shutting it down because of one case. I’m freezing it because we cannot establish that the process was properly controlled.”
She looked at Brenda.
“Preserve every complaint and approval record.”
Then Martin.
“Payroll logs, adjustments, reversals, reimbursements, and coding history.”
Finally, Blake and Derek.
“No changes to existing records without documented authorization. And no private discussions with affected employees about their cases outside the review process.”
Blake’s expression hardened.
“This is an overreaction.”
Claire reached for the phone.
“Get Legal involved.”
Then she stopped.
“Actually, outside counsel.”
Blake stared at her.
“You’re bringing in outside lawyers?”
“Yes.”
“Over Evan’s paycheck?”
“No.”
She pointed to Martin’s laptop.
“Because that paycheck just exposed a program affecting 214 employees.”
Then she looked at me.
“Evan, you’re leaving today. You’ll still be paid through the end of your notice period.”
I froze.
“Am I being fired?”
“No. I don’t want you returning to Operations while the records are being secured.”
Derek looked at me as he left.
Not frightened.
Accusing.
As if I had created the problem simply by revealing it.
That afternoon, I drove home with my cardboard box.
Sarah was waiting in the driveway.
“Well?”
I placed the pay stub on the kitchen counter.
“The CEO didn’t know how bad it was.”
Sarah raised an eyebrow.
“Didn’t know, or didn’t want to know?”
“I think she genuinely didn’t know.”
“That doesn’t make it okay.”
“No.”
And she was right.
Claire had been responsible for understanding what was happening in her company.
But the problem was bigger than one uninformed executive.
Operations saw project costs.
HR saw completed forms.
Finance processed payroll codes.
Executive reports showed routine inquiries being resolved.
Employees were the only ones experiencing the entire system.
Several days later, outside counsel contacted me.
I agreed to an interview.
I brought everything.
Emails.
Pay stubs.
Photographs.
The Apex service report.
Derek’s internal allocation form.
They asked precise questions.
Had Blake personally ordered Derek to change the classification?
“I don’t know.”
Had Blake ever told me to falsify anything?
“No.”
Had Derek threatened to fire me?
“No.”
Did I believe assignments changed after I challenged deductions?
“I suspected it, but I couldn’t prove why.”
I refused to exaggerate.
The facts were already serious enough.
Over the following weeks, investigators interviewed other employees.
Stories emerged.
A technician had been charged after a customer changed a project schedule and created overtime.
A production specialist lost money over scrap caused by an approved design revision.
Several employees had been charged for shared tools later found in supervisors’ storage.
Others received attendance penalties tied to company travel delays.
Not every complaint was valid.
One employee had damaged equipment through clear negligence and signed a separate repayment agreement.
Another had misused a company vehicle.
The investigation wasn’t about declaring every worker innocent.
It was about determining which charges had a factual and lawful basis.
About 6 weeks after my resignation, Sterling began issuing provisional corrections for clearly unsupported deductions.
Julian called first.
“They returned my tool charges.”
“All of them?”
“All 3.”
Then another technician received money.
Then Arthur.
The refunds began quietly while the broader investigation continued.
Several months later, the final audit findings were released internally.
The original $1 million figure had covered only the payroll codes Martin identified in Claire’s office.
Investigators found additional affected compensation categories and related payroll errors.
When repayments, tax corrections, applicable interest, and other remediation were included, the total cost to Sterling reached millions.
The company announced that several adjustment categories would be permanently discontinued.
Employees would receive individualized decisions.
Disputed cases could be appealed to independent reviewers.
Then came the management consequences.
Investigators discovered that Derek had submitted significantly more employee adjustments than most other operations managers.
Some were supported.
Many were not.
They also found emails showing how he responded when employees challenged him.
Take ownership.
Cheap lesson.
The system needs teeth.
In one case, an employee challenged a charge caused by a customer changing a project’s scope.
Derek replied that reversing deductions whenever someone complained would weaken accountability.
That email explained everything.
The goal had shifted from determining responsibility to discouraging complaints.
Derek was terminated for repeated misuse of the policy, unsupported classifications, and documented retaliatory conduct.
Blake’s case was more complicated.
He hadn’t personally approved every deduction.
Investigators found no evidence that he had directed Derek to falsify Apex’s records.
But he had designed the program.
He had connected management performance to project-cost recovery.
And he had ignored warnings that managers were using financial penalties too aggressively.
The board removed Blake’s authority over employee compensation and field operations, eventually moving him into a narrower strategic role.
Some employees thought he should have been fired.
Part of me agreed.
But I also understood that fairness meant judging each person’s actual conduct, not simply choosing the harshest punishment.
My individual reimbursement notice arrived shortly afterward.
Apex deductions: reversed.
Missing-wrench charge: reversed.
Customer survey charge: reversed.
Documentation penalty: reversed.
Two attendance deductions were reviewed.
One was reversed.
One remained.
Sarah read the notice.
“They kept that one?”
“Yes.”
“Were you actually late?”
I thought about it.
“Yes.”
“Then it’s fair.”
I laughed.
She was right.
The money returned to us was substantial.
We rebuilt our savings, cleared the credit card debt from those difficult months, and finally enrolled Lily in the art program she had missed.
Arthur received more than $10,000 because his unsupported deductions had accumulated over several years.
He called me crying.
“My wife thought I was terrible with money.”
I didn’t know what to say.
For years, many of us had blamed ourselves for financial instability that was partly being created by the company.
The repayments couldn’t undo everything.
But they mattered.
Months later, Claire asked whether I would participate in 3 paid consulting sessions while Sterling redesigned its compensation policies.
I agreed, after clearing the limited work with my new employer.
I wasn’t returning as an employee.
I simply understood what had failed.
During one session, a younger engineer asked:
“So are you saying employees shouldn’t be accountable for mistakes?”
“No,” I replied.
“I’m saying accountability shouldn’t be a surprise.”
The redesigned policies protected base wages, established transparent bonus formulas, and required proper evidence and independent review before any lawful financial adjustment.
Managers could still discipline employees for legitimate misconduct.
But they could no longer invent paycheck penalties based on vague responsibility labels.
During the final session, Blake approached me.
“Evan.”
“Blake.”
He looked uncomfortable.
“I owe you an apology.”
I waited.
“I still believe employees should care about the financial consequences of their decisions.”
“So do I.”
“But I thought making them bear those consequences would encourage ownership.”
I looked at him.
“Owners get upside.”
He stopped.
“They also get information,” I continued. “Decision-making authority. Control.”
Blake nodded slowly.
“We gave you responsibility without those things.”
“You gave us the losses.”
He looked down.
“Yes.”
For once, he didn’t defend the slogan.
And that mattered.
I didn’t need to become his friend.
I didn’t even need to forgive everything.
I only needed him to understand what had been wrong.
About 1 year after my resignation, Claire invited me to lunch.
We met at a diner near the interstate.
Halfway through breakfast, she placed a folder beside my plate.
I stared at it.
“No.”
She laughed.
“You haven’t opened it.”
“Still no.”
“It’s a job offer.”
“For what?”
“Director of Field Reliability.”
I smiled.
“You created a position.”
“We need someone who understands what happens in the field and what happens when executives design policies without listening to the people affected.”
“Higher salary?”
“Yes.”
“Less travel?”
“Yes.”
“Direct access to senior leadership?”
“Yes.”
I looked at the folder.
A year earlier, I would have given almost anything for that opportunity.
Now it was sitting in front of me.
And I didn’t want it.
“Claire, I appreciate the offer.”
“But?”
“But Sterling had 6 years to value my work while I was there.”
She nodded.
“That’s fair.”
“I’m glad the company changed. I’m glad people got their money back. I don’t want Sterling to fail.”
“I know.”
“But fixing the system doesn’t erase why I had to leave.”
For several seconds, she said nothing.
Then she closed the folder.
“I understand.”
She didn’t argue.
That mattered more than the salary.
My new job at Vanguard Automation had become predictable in the best possible way.
I still worked hard.
I still traveled.
But when payday came, the numbers made sense.
When something changed, I received an explanation.
And when I disagreed with a manager, I could ask questions without worrying that my paycheck would mysteriously shrink.
Lily eventually returned to art class.
Then, 6 months later, she announced that she wanted to play soccer instead.
For a moment, I almost objected.
Art class had come to symbolize everything our family had nearly lost.
Sarah stopped me.
“It’s her hobby, Evan.”
She was right.
Lily didn’t need to keep painting to prove our family had recovered.
We signed her up for soccer.
She was terrible.
She loved it.
And watching her run across the field without knowing what we had once sacrificed to pay for those ordinary childhood experiences was worth more than anything Sterling could have offered me.
Years later, I became a supervisor at Vanguard.
When one of my engineers made a costly mistake, I remembered Sterling.
Instead of immediately assigning blame, we investigated.
The engineer had made an error.
But the process had also failed.
A verification step was missing, software safeguards were inadequate, and the schedule had been rushed.
We corrected the system and coached the employee.
Nobody invented a surprise deduction.
That experience confirmed something I had learned the hard way.
Accountability didn’t have to mean arbitrary punishment.
And a workplace where employees could question decisions was stronger than one where they were afraid to speak.
I sometimes thought about my final morning at Sterling.
The cardboard box beneath my desk.
The photograph of Lily laughing.
The resignation letter on Claire’s table.
And the pay stub showing exactly $312.64.
For years, I had told myself that each unfair deduction was too small to challenge.
$200.
A missing wrench.
A customer survey.
A disputed responsibility form.
One bad paycheck.
I kept waiting for things to get better.
Instead, the system learned that employees would absorb the losses quietly.
Until one day, I couldn’t anymore.
When Claire asked why I was leaving, I finally told her the truth.
That one conversation led to an investigation, substantial repayments, management consequences, and a company-wide reform.
But the most important change wasn’t the money returned or the people disciplined.
It was that employees finally had somewhere independent to go when something was wrong.
They no longer had to wait until they were carrying a cardboard box toward the exit before they felt safe asking questions.
Because the most dangerous workplace isn’t always the one where everyone complains. Sometimes it’s the one where nobody believes complaining will change anything.
💬THE END! THANK YOU FOR READING! ❤️🙏